Friday, 10 February 2012

Diary of an IFA - Adviser Blog

"Diary of an IFA" - written to be featured in FT Adviser

Diary of an IFA

Monday

The day starts at 5:30am in the form of a human alarm call from baby Sophie.  Although she’s only a month and a bit old, her sleep patterns are settling down and 5:30am is a bit of a luxury.  Once the morning feed is done, and breakfast and a nice strong coffee are consumed, it’s off to the office for client Research and checking emails.

Then it’s off to the first meeting at 11am with a new client.  The lady in question runs a training business and received some investment advice from one of the banks.  The investment had been running for 6 years and had made a loss.  There had been no annual reviews and the client had now been told the bank in question no longer provides advice.  I found this disappointing, but ultimately not surprising.  Then it’s back to the office for some client research, checking emails and meeting preparation.

Tuesday

The day starts with a call from the head of a prominent local chamber of commerce.  We are currently working together to ensure that the businesses who are members of the chamber are prepared for Auto Enrolment.  We discuss the fact that the auto enrolment date has been put back for most SME’s and how they will react to this news.  Chamber head believes that many businesses may decide to defer making provisions for an additional year, I hope they use the additional year to prepare for auto enrolment more gradually.
Later on in the day, I received a call from an existing client.  His private medical cover is up for renewal and he wants to make sure he is receiving a decent deal on the renewal.  We speak and he emails the documents over for me to take a look at. 

More research for existing clients followed by a trip to the local gym.  My 8 year old, Charlotte practices Jujitsu whilst I have the first circuit training session of the New Year.  I’ve got a feeling I’m going to ache in the morning!

Wednesday

It’s another early start this morning as the baby decides to wake at 5:00am.  I’m feeling the impact of the training session, but I’m hoping it’ll get better next week!  After breakfast and a strong coffee I’m ready for my 9:00am meeting with a new potential introducer to the business.  
Most of our work comes from working with fellow professionals and cross referrals in business.  The meeting goes well and we agree to meet up in a month to see how we can move our relationship forward.
A call comes through from a fellow financial planner who wants to work on a case with us.  I’ve known her for years but have renewed the relationship through connecting via social media.
  

Thursday

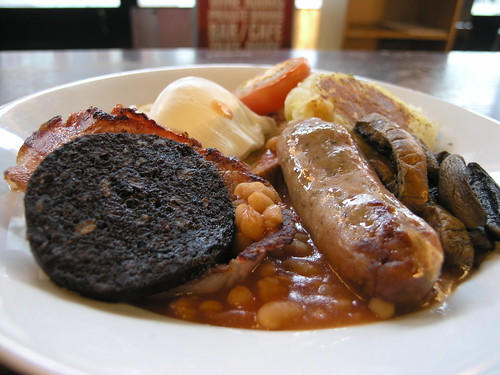
The day starts early with a networking meeting at a pub in Theydon Bois, Essex.  I enjoy my first post new year fried breakfast, however I might have to worth extra hard in the gym to burn it off!       
Then it’s on to a meeting with one of our solicitor introducers.  They are professional trustees on behalf of a number of clients and when they feel appropriate approaches us to provide investment advice on behalf of the client.  

We agree to the fee structure for the initial report and they ask me to conduct the work required on behalf of the client.  Another meeting follows with another solicitor and a life coach who specialises in helping the newly retired.  We meet in a little village pub in rural Essex and discuss how we may be help each other move our businesses forward.  We share some great ideas and go our separate ways.

Friday

The first meeting of the day is with one of our main introducers.  I talk about getting used to having a new born in the house again and lack of sleep.  He tells me about his Christmas trip to Dubai.  The meeting went well, however I did feel slightly envious of his January tan.
Then it’s on the train to sunny Essex for my last two meetings of the week.  I make this meeting with 2 minutes to spare with a HR consultant introducer.  During our conversation, he tells me about his client he wants me to contact as they need advice on how to prepare for auto enrolment.

Then it’s on to meeting number 3, where I meet with a commercial insurance broker to see how we may be able to help his clients.  As its 5pm on a Friday, the meeting is held over a pint.  I’m happy with the week’s activity, with new business opportunities coming to fruition and some productive longer term relationships which are starting to develop.  I’m doing Sophie’s overnight feed tonight though, wish me luck!

Thursday, 9 February 2012

Top Financial Twitterer's - Part 1

During a presentation for a networking event last week, I mentioned that one of my favourite money related mobile money app's was Twitter.  If you want to see why twitter is a great money tool you can read this Blog

One of the questions asked at the end of the presentation was....

"Fine, so Twitter is a great application for great financial tips and links to additional resources....but with so many so called 'money experts' on Twitter, who do you trust?"

So, in this entry I'm going to give you 3 of the top money related people to follow on twitter.  Also, I'm going to do an entry weekly with 3 new twitterer's.  So if you're reading this and you're not on here don't be offended, I'm sure you'll be on here soon!

Anyway, the first 3 entries are:-

@PeteMatthew - why?  I'm a great believe in ensuring everyone has the required information to make informed  financial choices....and there is no-one who does more to provide great content than Pete Matthew.  Please do check out his videos on this site....Pete is demystifying the world of money one video at a time!

@Pensionsmonkey - I'm sure you've seen Tom before (the man behind the Monkey!) as he is always popping up on BBC breakfast.  Worth following for his in depth pension's knowledge and always quick to comment on the latest news and changes.

@CashQuestions - Annie Shaw who is an active tweeter who provides a great service with her website.  It's a simple idea but incredibly effective....Ask a money related question and get it answered by a financial expert, for free.  Whilst this doesn't replace professional financial advice, it will give you a starting point or a greater understanding of your area of concern....and that's got to be good thing.

Keep looking out for more entries into the top money twitterer's....there will be more coming next week.

Tuesday, 7 February 2012

Should your next move be into a Corporate environment or should you consider an SME?

This Blog entry was written as a guest post for the GAAPweb Blog

So, let’s assume you’re looking for your next opportunity to develop your career and feel that you feel that you can’t fully utilise your skills in your current role.  Let’s also assume you have two opportunities on the table, one with a large corporate organisation and another with a medium sized niche practice.  A natural assumption is that the opportunities, potential career progression and scope of work within the corporate environment would be greater due to the size of the organisation.  Whilst on many occasions these assumptions are correct, is it worth considering looking at the smaller business.

Personally, I’ve been on both sides of the fence.  I now run a small financial planning business but have worked for large corporate organisations for the majority of my career.  So, in my experience, how does the corporate environment compare with working within a SME practice environment?

Firstly, I don’t believe I would have launched my business without having the training, development and supportive environment of a large business.  I also believe that if you are at the early stages of your career, a larger corporate environment tends to provide more support in helping develop your skills than a smaller niche professional practice can.

However, and I’m sure it depends on the culture of the business you work in, I reached a stage in my career when I wanted to broaden my portfolio of skills, build my own long term professional relationships and start to develop my own systems and practices. 

In my experience taking this element of control can be particularly tough in a corporate environment and it tends to be easier to develop as a professional (once a certain level of competence has been achieved) in a smaller niche practice.
Within my business we encourage our staff to share ideas, take on new projects, develop new business opportunities and suggest changes to our systems to make the way we work more efficient. 

This culture was developed based on my frustration of working within a large corporate where sometimes that creativity was stifled. 

Therefore the question I believe you need to ask yourself is, does the opportunity you are considering offer the opportunities, flexibility and scope to build as a professional?   

Tuesday, 31 January 2012

Adviser Blog - are the changes in financial services an opportunity, a threat or both?

Originally written for inclusion in FT Adviser - Letter of the week.

Firstly let me say this, I appreciate the fact that some of the upcoming changes in our profession are unsettling to say the least.  However one thing you can be sure of, especially in our world, is constant change.  Therefore one thing I can’t understand is the constant flow of letters in the trade press and posts of financial forums bemoaning RDR.  Surely at this late stage most advisers and advisory firms have made one of two choices, either to prepare for the upcoming changes or to leave the business.

Whilst RDR provides a challenge, it also provides a range of opportunities for the professional advice community.  It also means that there is more focus on a  IFA’s looking at their existing business model and moving towards a more sustainable (post RDR) business model and a move towards more clients receiving a high standard of ongoing service, and surely that’s a good thing.

Also, I believe there will be a greater demand for advice in the corporate / SME business market due to the introduction of auto enrolment.  Whilst there are certain firms which are active in the market, there doesn’t seem to be enough to meet the potentially overwhelming demand of firms seeking advice to prepare for the upcoming changes they will need to make.  I believe that the business demand, if we position ourselves correctly will be ready to take these opportunities.

However one concern I have is that a large part of the population may not have the opportunity to seek affordable independent financial advice at a time when they may need it the most. 

Any advice business needs to ensure they remain commercial and unfortunately all of us need to make a sensible decision about who we can afford to provide our service too.  I suspect that the internet will play a part in filling this gap providing a low cost guided solution, so it will be interesting to see how either web based financial guidance (or web based advice) may develop over the next year or so.

UNUM's latest marketing - what do you think?

UNUM, a life and health insurance provide have come out with this recent video to promote their income protection product.  Whilst we would always encourage you to shop around for the best deal, either independently or through an adviser, I've got to say I'm quite impressed with the advert.  What do you think of it?

Why an addition to the family means another visit to your financial planner...

As many of you who read this will know, we've recently had a new addition to the family.  Little Sophie was born at the end of November and our life is back to sleepless nights, constant feeds and having to plan with military precision how we get everything we need in the car when we decide to take a trip anywhere.

So, what has this meant to our personal finances.  Firstly, it means life has just become more expensive.  A recent study by LV= places the cost of raising a child at £218,024 in total with the main cost being education (which has increased by 120% since 2003)

One of the main reasons for the huge increase is the rule change in tuition fees and whilst many young people will fund this with student loans, many parents want to ease the burden post university by planning to contribute toward these fees.  This is where a relationship with your financial planner should come into play.

However there is another fundamental reason you should see your financial adviser if a new arrival comes along....the need to review your existing protection needs.  In our household the arrival of Sophie meant that our life cover designed to protect our family needed to be reviewed.

So, you may be asking why?  Before Sophie arrived all our family protection policies were due to finish when Charlotte was 21.  However if I kept the same policies in place without reviewing these plans they would finish when Sophie was 13....meaning that I've got a gap in the cover needed to protect my family until Sophie was 21.  Therefore, it's important I look at the options to ensure this gap is filled.

So, a couple of questions....

When was the last time you reviewed your protection needs?

Was the last time you saw your financial planner since an addition to your family?

What action are you going to take to ensure you have the peace of mind to ensure your family are protected?

Wednesday, 25 January 2012

Money on the go - the 6 top financial mobile apps

Mobile App's are brilliant aren't they?  You can play games, keep up to date on the latest news, or keep in touch with friends via social media...all from your Mobile or Tablet computer.  However, are there any applications which allow you to manage your money more effectively using the power of technology?
The answer is yes, there are plenty out there, but what ones are genuinely useful?  Below are our favourite top 6 financial mobile applications.  

But firstly an apology...I'm an Iphone user and therefore these applications are Iphone focussed, therefore I'm sorry if these App's are not available on your mobile of choice.  However I'm sure that if you're not an Iphone user, you can find something pretty similar available on your phone....anyway, onto the list:-

Iexpenseit - (Lite version - free, Full Version £2.99)

Whilst many of our clients understand exactly their month to month financial situation, we have a few who find it hard to keep track of their outgoings every month.  This is completely understandable as it can be tough to keep track of what you spend as you go about your daily business.  Iexpenseit goes a long way to solve that problem.

The application allows you to record your income, and more importantly, your expenditure on the go.  You can add multiple accounts (so it can potentially be used for personal and business accounts) and has the facility to provide PDF reports (illustrated with some nifty little charts) at the touch of a button.

The Lite version allows you to enter 200 entries, so you can try before you buy.  However with the cost at a reasonable £2.99 it offers a low cost way to manage your day to day expenditure.


AVIVA Time to Act (Free)

This nifty little free app, which is sponsored by Aviva, provides you with a rough and ready indication of whether your current retirement provisions are enough to live on in later life.  

When you put your annual salary, existing pension fund, contributions, retirement age and attitude to risk into the app it will provide you with the amount you are entitled to in tax relief but more importantly provide broad projections of what you may receive as an income in retirement based on the data you input.
  
Whilst this isn't an app you'd use every day...it's interesting to see if what you believe is a sufficient amount to save for retirement is actually enough.  It also allows you go back and play with the numbers to see what difference paying a little extra contribution might make, or if you retired 5 years later, or if you were prepared to take a little more or less risk.

There's also a similar app available on Android called Nest Egg for all you non Iphone users....

Bloomberg (free)

Whilst many people use the Bloomberg application for tracking individual share portfolios, it can also be used to get up to date information on your Investment ISA's, Pension Funds and Unit Trust investments.

Just type the name of your fund into the App (be careful you select the correct fund and if in doubt contact your adviser) add it to your favourites list and it allows you to keep track of how many of your investment funds are doing right on your phone.      

However please bear in mind by their nature many of your investments will fluctuate and therefore bear this in mind when keeping track of the investment performance in your funds.

Inflation Calculator (69p)

This application provides historical data of how prices of goods and services have increased over the years.  Select any year from 1800 to last year and it will give you an indication of how prices of changed.  

So, why is this important?  Whilst we can't predict what increase in the cost of living will happen in future years, it clearly illustrates that the value of your money is eroded over time.  

This could potentially help you make the right savings and investment choices so that your money has a fighting chance to keep up with this inflationary rate and therefore maintain it's true value.

RedLaser (free)

What use is money if you can't spend it on the things you enjoy?  However ensuring you get the best deal on your purchases is important and RedLaser can help you achieve this.  

You can use RedLaser to scan the bar code of many potential purchases to ensure the deal in the store you are in is competitive.  RedLaser does the hard work and does a search online for the best deal on that new potential purchase.  It can also be used to find the nearest shop with the best deal, and includes a QR code scanner as part of the bundle.

It's important to note that the database doesn't include all retailers and you may be able to get a more competitive deal by shopping around yourself.  However as a quick method of seeing whether the deal where you are is overly expensive or actually pretty competitive it's a nice piece of kit.

and lastly....

Twitter (free app)

Ok....so it's not strictly speaking a money related app....but Twitter is incredibly useful as a financial resource for a number of reasons.  Firstly, there are many financial professionals willing to share knowledge, provide tips and interact on a range of money related subjects.  

Secondly, although as you may know, the content is limited to 140 letters, there is a steady flow of useful links to more in depth analysis on many different aspects of money.  Thirdly, it's fun!!

So, who should you follow on twitter to benefit from these resources.....I think I'll leave that for another blog entry.